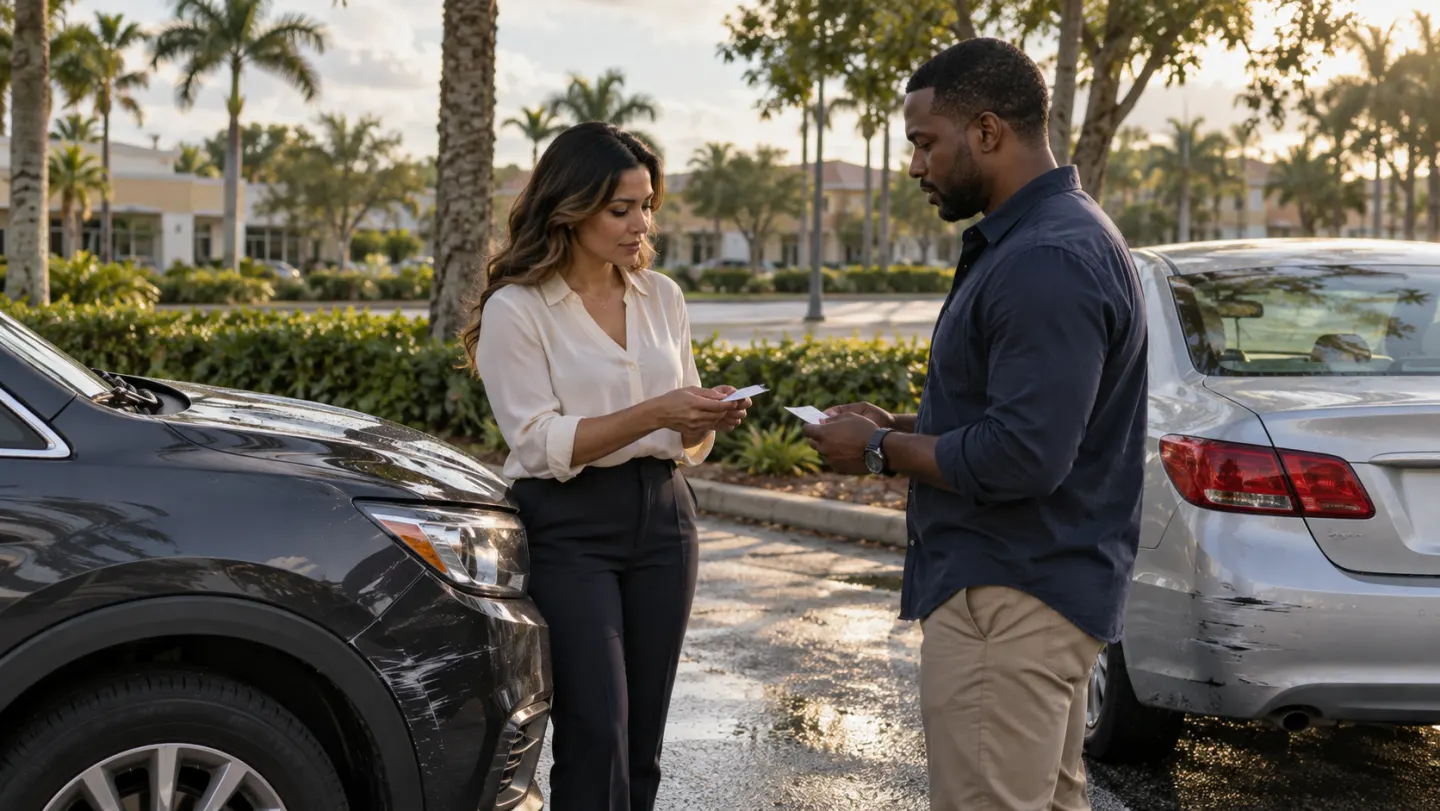
When another driver causes a Florida car accident, you still need to take an active role in documenting the crash and handling the resulting claims. Exchange information, report the collision, seek appropriate medical care, and contact your insurer.
An admission at the scene may be useful information, but it does not answer every question about insurance coverage, injuries, or payment. Keep records from the beginning so you can respond if the accounts change or a claim is disputed.
Complete the immediate steps at the scene
Call 911 for injuries or an immediate hazard. Provide the identifying information Florida requires, including your name, address, vehicle registration number, and an available driver’s license upon request. Collect insurance and contact details as well.
Contact law enforcement and follow reporting instructions. Florida’s Department of Financial Services recommends reporting the accident even when it appears minor.
Avoid making a private payment agreement before you understand the damage and your medical condition. Keep the conversation focused on safety and exchanging information.
Build a clear record of the other driver’s actions
Evidence should explain how the collision occurred. Photograph the scene safely, preserve dashcam footage, and obtain witness contact information.
Write down relevant details such as which lane you occupied, whether you were stopped, and what you saw before impact. If the other driver sends messages about the crash, preserve the original conversation.
A useful record does not need dramatic language. “I was stopped at the red light when I felt an impact from behind” explains more than a general statement that the other driver was careless.
Identify which insurance covers each loss
Different parts of an accident claim may involve different coverage:
| Concern | Coverage that may apply |
|---|---|
| Qualifying medical expenses | Applicable PIP coverage |
| Damage to your vehicle | Other driver’s property-damage liability or your collision coverage |
| Injury losses caused by the other driver | Available bodily-injury liability coverage |
| Insufficient or absent bodily-injury coverage | Your UM/UIM coverage, if available |
Each policy has its own terms, limits, and exclusions. Do not assume that having the other driver’s insurance card guarantees payment for every loss.
Address medical care before waiting on a liability decision
Seek appropriate evaluation for symptoms after the collision. Explain the crash date, your initial symptoms, and any changes since then.
Florida PIP medical benefits generally require qualifying initial services within 14 days. That condition applies even when someone else caused the crash. Benefits remain subject to eligibility and coverage limits; the rule does not require you to finish all treatment within 14 days.
Keep medical decisions focused on your health. Follow-up visits should reflect the clinician’s recommendations and your condition, not an effort to reach an assumed settlement amount.
Keep insurance communications accurate and organized
Notify your insurer promptly and review your policy’s reporting and cooperation requirements. Keep claim numbers, adjuster names, and copies of correspondence in one place.
Before a detailed statement, clarify who the representative works for and what information is being requested. Answer accurately, and say when you do not know or remember something.
If a request is unclear, ask for it in writing. Your obligations to your own insurer can differ from your position with the other driver’s insurer, so seek guidance about disputed or unfamiliar requests instead of ignoring them.
Understand what happens when fault is contested
The other driver’s insurer may disagree with your account or argue that you contributed to the collision. Florida generally reduces damages according to a claimant’s share of fault, with a recovery bar above 50 percent in negligence actions covered by that rule.
Ask what facts support the insurer’s position. A disagreement about a traffic signal, turning movement, or sequence of impacts may require evidence that was not included in the initial claim submission.
Preserve documents even if they seem unfavorable. A complete, accurate account is essential to evaluating the matter.
Review compensation and settlement terms carefully
Document medical expenses, lost income, and other claimed losses. Keep receipts and employer records rather than relying on a rough total.
Pain-and-suffering claims can involve Florida’s statutory injury threshold. Where applicable, § 627.737 requires a qualifying injury, such as a permanent injury within a reasonable degree of medical probability, or another listed category.
Before signing a release, understand which claims it closes. If an underinsured motorist claim may remain, have the statutory settlement-notice requirements checked first.
Confirm the deadline for legal action
Recent Florida negligence injury claims generally carry a two-year lawsuit limitation period. The applicable date can depend on the claim and exceptions, so do not assume every accident-related claim follows the same schedule.
Keep both the accident date and all insurance correspondence available when asking an attorney to review the deadline.
How Invictus Legal can help
Invictus Legal invites people with accident-related questions to request an initial consultation. Explain what happened, identify any unresolved insurance issues, and ask whether the firm may be able to assist with your situation.
Important note
This article provides general information, not legal advice. Rights, coverage, deadlines, and outcomes depend on the facts and applicable law. Contacting Invictus Legal does not create an attorney-client relationship. Representation requires case evaluation, conflicts review, and a written agreement.
Sources and further reading
- Florida Statutes § 316.062 (information exchange and assistance).
- Florida Statutes § 627.736 (PIP benefits).
- Florida Statutes § 627.737 (motor-vehicle tort threshold).
- Florida Statutes § 627.727 (UM/UIM coverage and settlement procedures).
- Florida Statutes § 768.81 (comparative fault).
- Florida Statutes § 95.11 (limitation periods).
- Florida Department of Financial Services: Automobile Insurance Toolkit and Filing an Auto Claim.